
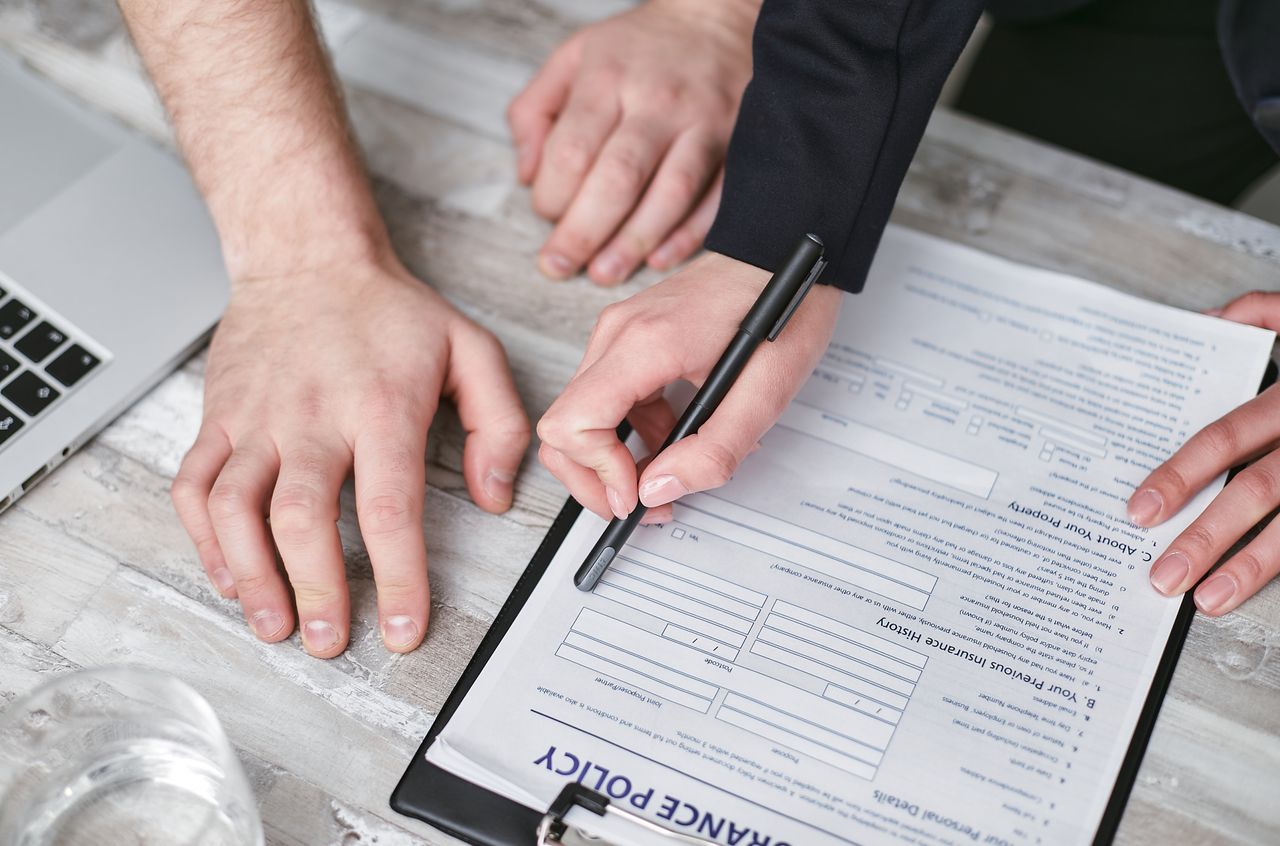
Nine out of ten South Africans carry no life cover at all. Not “not enough.” None. That figure comes from the Financial Sector Conduct Authority’s 2022 review of the sector, and little suggests the number has moved much since.
Meanwhile, the country’s collective life and disability insurance shortfall sits at R50.4 trillion, seven times the size of South Africa’s entire economy, according to the Association for Savings and Investment South Africa’s latest Insurance Gap Study. That is not a rounding error. That is 16.1 million working South Africans, on average, holding cover for less than 40% of what their families would actually need if they died or could no longer earn an income.
Last month, we showed the difference between a family that inherits a formula and one that inherits a plan. Insurance is the tool that builds the plan before anyone needs it, and it is far less complicated, and far cheaper, than the fear around it suggests.
Insurance carries a stigma in South African households that numbers alone will not fix. It gets treated as a topic for later: for when there is more money, for after the wedding, or the bond, or the baby. That instinct is understandable. Nobody wants to spend a Tuesday afternoon pricing out their own death. But the avoidance has a cost, and it does not fall on the person avoiding it. It falls on whoever is left behind. For the 32% of South African women who define financial independence as being able to support their family, according to a 2024 Bank of America study, the maths is direct: independence does not end when the income does, unless something is in place to continue it.
The complication is not a lack of products. South Africa has one of the most developed insurance markets on the continent. The complication is that most people cannot tell you what type of cover they actually hold, whether it would pay out, or to whom.
1. Two Families of Insurance
South African law splits insurance into two families: life, called long-term, and non-life, called short-term. Long-term insurance protects people. It covers your life, your ability to earn, a disabling injury, or a severe illness, and it answers to the Long-Term Insurance Act, with disputes going to the Ombudsman for Long-Term Insurance. Short-term insurance protects things and the liabilities attached to them: your car, your home, your possessions, under a separate Act and a separate ombud. The Financial Sector Conduct Authority sits over each. Understand the split, because one will never do the other’s job. A paid-up car policy pays out a wreck or write-off. It will never replace a salary.
Medical aid is where the real confusion sits. It is not insurance in the legal sense. It is a non-profit scheme under the Medical Schemes Act, required to cover a defined list of serious conditions and barred from turning you away for your health. The actual insurance product in this space is gap cover, which pays the difference between what your scheme settles at its rate and what a specialist bills, a gap that can run into tens of thousands of rand on one hospital stay. You cannot hold gap cover without an active medical aid underneath it.
2. How Much Is Enough
How much cover is enough has an actual formula, not a guess. Financial planners commonly size life cover at 8 to 15 times annual income: 5 to 8 times for a single person with debt and no dependents, 10 to 15 times for a young family with a bond and small children. A sharper version adds up four specifics, known as DIME. None of this needs to be expensive. A healthy 35-year-old non-smoker typically pays R150 to R350 a month for R1 million of life cover, moving to R240 to R450 in their 40s, based on 2026 industry pricing.
D — Debt: home loan, car finance, credit cards, student loans
I — Income replacement: 10-15 years of take-home pay
M — Mortgage bond / major expenses: any remaining bond not covered above
E — Education: university fees, school fees for dependents
If the budget stretches to a single policy, prioritise differently than instinct suggests. Death gets the attention. Disability does the greater damage. ASISA’s data shows the average South African family needs R3 million in disability cover but holds R1.2 million, and unlike a death benefit paid once, a disabling illness or injury stops income while expenses climb, because the household size does not shrink. Income protection or disability cover, not life cover alone, is where a first policy should start.
Did you know? Closing South Africa’s death and disability insurance gap would cost the average earner about 8.2% of their income, according to ASISA. That figure sounds large until it is set against the 37% cut in household spending a family faces if a breadwinner becomes disabled without adequate cover.
3. The Tax-Free Payout
The tax treatment makes the case for wealth building sharper still. Premiums on life, disability, and income protection cover are not tax-deductible, but a matching exemption means the payout to a named beneficiary is completely tax-free, one of the few places in the tax code where the receiving side wins outright. Nominate a person directly, rather than your estate, and the money also bypasses the frozen-estate delay covered last month, along with the estate duty of 20% or more on amounts above the R3.5 million abatement. A signed beneficiary nomination form does more for your family’s liquidity than most investment decisions you will make this year.
Insurance will never feel like the fun part of a financial plan. It is not a TFSA, and it will not compound into a retirement lifestyle. But it is the one instrument that guarantees an outcome regardless of what happens to markets, your health, or your income between now and the day it is needed.
“Death and taxes are the two certainties life offers. Insurance decides what your family does about the first one.”
Death and taxes remain the two certainties life offers everyone. Insurance decides what your family does about the first one: improvise under pressure, or execute a plan you already paid for.
Your Wealth Checklist
- Work out what your family would need if your income stopped tomorrow, using the DIME method: Debt, Income replacement, Mortgage, Education.
- Size your life cover at 8 to 15 times annual income, more for a young family with a bond, less for a single earner.
- Prioritise disability or income protection before life cover if a budget stretches to one policy; disability does the greater financial damage.
- Confirm whether your employer’s group cover follows you if you resign. Most of it does not.
- Check that you hold gap cover alongside your medical aid, and understand that medical aid is not insurance in the legal sense.
- Name a beneficiary directly on every policy, not your estate, so the payout is tax-free and skips the frozen-estate delay.
- Review your cover after any major life event: marriage, a child, a new bond, or a jump in income.
- Consult an FSCA-registered (Financial Sector Conduct Authority) adviser before signing.
Start small if you must, but start. Price a term life policy this week. Check whether your employer’s group cover actually follows you if you resign. Ask what would happen to your household if your income stopped tomorrow, not for a day, but for good. If the honest answer makes you uncomfortable, that discomfort is the most useful financial signal you will get this month.
Next month, this series turns from protecting your income to growing it: why the ROI on your own education and skills can outperform most portfolios you will ever build.
This article is intended solely for informational purposes. The content does not constitute financial advice of any nature whatsoever and should not be relied upon as such. The decision to invest and the suitability of any investment choice is solely your responsibility. While every effort has been made to ensure accuracy, it is recommended that you consult with a qualified FSCA-registered financial adviser before making any financial decisions. The writer and the publisher assume no responsibility or liability for any errors, omissions, or actions taken based on the information provided.

Leave a Reply