
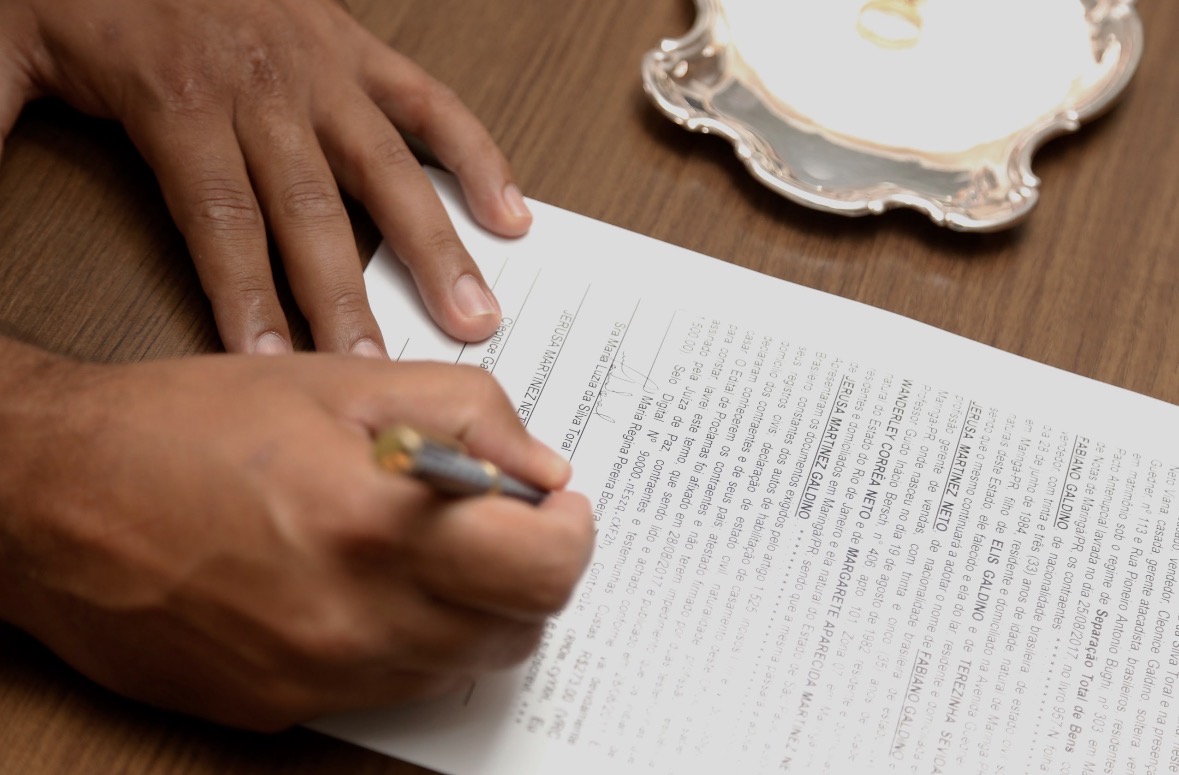
A will is the one financial document you write for a day you will not be present to manage. This column covers what a will legally requires, what that Act does without one, and the decisions to close out before the year ends.
September is National Will Month: without a signed, witnessed will, the Intestate Succession Act writes one for you, using a formula fixed in 1987 that has never met your family, your partner, or your children.
“A will is the one financial document you write for a day you will not be present to manage.”
1. What a Valid Will Actually Requires
The Wills Act 7 of 1953 sets a low procedural bar: you need to be 16 or older, and the document must be in writing, handwritten, typed, or printed. You sign every page, and 2 competent witnesses aged 14 or older sign in your presence and in each other’s presence. A witness who stands to inherit under the will forfeits that inheritance, so choose witnesses with nothing to gain. No lawyer or notarisation is required. Cost and complexity are not valid excuses: most invalid wills fail on a missed signature, not a missed legal fee.
National Wills Week, the Law Society of South Africa’s (LSSA) mid-September initiative, gives you a free will through a participating attorney, who cannot insist on being named executor: you keep that choice. Banks run a similar-looking free service through their trust divisions, on different terms. Accept a bank’s free will, and it becomes sole executor, entitled to the maximum statutory fee of 3.5 % (plus VAT) on your gross estate, a fee your family cannot negotiate down or remove without a court order. Free is not the same as neutral.
Did you know? 85 % of women would rather talk about end-of-life with family or friends than about money. Source: Bank of America, 2024.
2. What the Intestate Succession Act Does to Your Estate Without One
Die without a will, and the Intestate Succession Act 81 of 1987 applies a fixed formula: a surviving spouse inherits the greater of R 250 000 or a child’s share, the estate split by the number of children plus 1, and the children split the remainder. That formula assumes a married household and does not recognise an unmarried life partner as a spouse, regardless of the relationship’s length, so a life partner inherits nothing directly under the Act.
Consider Jonasi, 44, together with his partner Lesedi for 6 years, with 4-year-old twins, Hayley and Ashley, from a previous relationship. Jonasi and Lesedi are not married. They built a home together worth R 3.4 million, registered in Jonasi’s name. Jonasi dies without a will. Because Lesedi is not a legal spouse, the Intestate Succession Act sends the full estate to the twins, and because Hayley and Ashley are minors, that money goes into the Guardian’s Fund, not into Lesedi’s hands. Lesedi, who paid half the bond for a decade, has no automatic right to remain and no capital and must approach the Master or launch a legal claim for anything.
Compare that to Joyce, 44, in the same situation. Joyce signed a will naming her partner as sole heir and set up a testamentary trust for her children with a trustee of her own choosing. Her life policy, R 2.5 million, pays out to her nominated beneficiary within weeks, independent of the estate. The difference between Jonasi and Joyce is not the size of the estate. It is who controls the outcome. Jonasi’s family inherited a formula. Joyce’s family inherited a plan.
3. Minor Children and the Guardian’s Fund
Without a testamentary trust, a minor’s inheritance is paid to the Guardian’s Fund, administered by the Master of the High Court. The fund pays around 7.25 % a year, a rate the Minister of Finance can adjust. Access before age 18 is not automatic: a guardian must apply to the Master and motivate the need, capped at R 250 000 of capital for costs such as school fees or medical bills. The full balance and interest are released at 18, on marriage, or a court declaration of majority. A testamentary trust with your own trustee keeps that decision with you, not a government official you have never met.
4. The Decisions You Must Make Before Year-End
An estate under administration is frozen: bank accounts lock except for limited maintenance releases, routinely for months. With 55 % of households needing to borrow or sell something in an emergency, and 78 % holding no emergency savings, a frozen estate is a second emergency stacked on the first (Deloitte, 2021; Old Mutual, 2019). Before the year closes, decide on an executor (a family member, an attorney, or a trust company willing to serve), name a guardian for any minor children, and list specific bequests for property or personal items you want to go to a named person, then get it all into a signed, witnessed document. Delay past December, and the same open questions carry into another year, with your family none the wiser.
5. Where a Will Fits Into the Rest of Your Estate Plan
A will does not control everything. Retirement fund proceeds fall under section 37C of the Pension Funds Act, whose trustees, not your will, decide how it is allocated among your dependants. Life policies pay directly to a nominated beneficiary, bypassing the estate entirely. Your will governs the rest: property, savings, business interests, and personal effects. Executor’s fees carry the same 3.5 % (plus VAT) cap noted above on the gross estate value, plus 6 % (plus VAT) on income collected after death. Estate duty is levied at 20 % on the dutiable value of the estate up to R 30 million, and at 25 % on any dutiable amount above R 30 million, after a R 3.5 million abatement per person. None of these numbers changes because you avoided the conversation. They apply either way.
Did you know? 66 % of South Africans still do not have a valid will, and the share of adults who have drafted one fell to 34 % in 2025, down from 39 % the year before. Source: Sanlam Legacy Wills Survey, 2025.
Your Wealth Checklist
- Confirm you meet the legal minimum: age 16 or older, will in writing.
- Nominate an executor and get their agreement in writing.
- If a bank offers a free will, confirm it does not require naming the bank as sole executor at the maximum fee.
- Name a guardian for minor children, and set up a testamentary trust rather than defaulting to the Guardian’s Fund.
- Sign every page in front of 2 competent witnesses aged 14 or older, none of them a beneficiary.
- Check the beneficiaries on your retirement fund, life policy, and unit trusts: they pay out independently of your will and can override it.
- Calculate your estate duty exposure above the R 3.5 million abatement, and budget for executor’s fees of up to 3.5 % (plus VAT) of the gross estate value.
- Store the signed original with your attorney, the Master of the High Court, or in bank safe custody, and tell one trusted person where.
- Review the will after marriage, divorce, a new child, or a major asset purchase. It does not update itself.
- Consult an FSCA-registered (Financial Services Conduct Authority) financial adviser or attorney before finalising a will involving a trust, offshore assets, or a business interest.
Next month, Wealth Creation 115 turns to insurance, the policies most readers already pay for but rarely understand, and the ones a frozen estate makes suddenly necessary.
This article is intended solely for informational purposes. The content does not constitute financial advice of any nature whatsoever and should not be relied upon as such. The decision to invest and the suitability of any investment choice is solely your responsibility. While every effort has been made to ensure accuracy, it is recommended that you consult with a qualified FSCA-registered financial adviser before making any financial decisions. The writer and the publisher assume no responsibility or liability for any errors, omissions, or actions taken based on the information provided.

Leave a Reply